Há 2 horas

O VOO DO CORVO ....... O Voo do Corvo pretende informar e contextualizar . Assim acompanhará diáriamente diversos temas e acontecimentos, de forma variada e abrangente nas áreas da Opinião e Noticiário. Nacional e Internacional. O critério Editorial é pluralista e multifacetado embora existam dois “partis/ pris”: A Defesa do Património e do Ambiente. António Sérgio Rosa de Carvalho.

The
Long-Term Fiscal Impact of Immigrants in the Netherlands, Differentiated by
Motive, Source Region and Generation
"The
Long-Term Fiscal Impact of Immigrants in the Netherlands, Differentiated by
Motive, Source Region and Generation" is a prominent economic study authored by Jan van de
Beek, Joop Hartog, Gerrit Kreffer, and Hans Roodenburg, published as an IZA
Discussion Paper. Using highly detailed administrative microdata from the Dutch
population in 2016, the authors calculate the total discounted lifetime net
fiscal contributions (taxes paid minus public benefits and services consumed)
across up to 87 source regions.
The paper
outlines several core findings regarding the long-term fiscal impact of
immigration:
1.
Differentiation by Immigration Motive
The net
fiscal impact of a first-generation immigrant is heavily determined by their
reason for entering the country:
2.
Differentiation by Source Region
The
geographical and cultural origin of immigrants correlates closely with their
net fiscal impact:
3.
Intergenerational Mobility & The Second Generation
The study
uncovers a unique paradox regarding the children of immigrants (the second
generation):

The
Long-Term Fiscal Impact of Immigrants in the Netherlands, Differentiated by
Motive, Source Region and Generation
https://papers.ssrn.com/sol3/papers.cfm?abstract_id=5077481
IZA Discussion Paper No. 17569
47 Pages
Posted: 2 Jan 2025 Last revised: 7 May 2025
University
of Amsterdam - Amsterdam School of Economics (ASE)
University
of Amsterdam - Faculty of Economics and Business (FEB); Tinbergen Institute;
CESifo (Center for Economic Studies and Ifo Institute); IZA Institute of Labor
Economics
Independent
CPB
Netherlands Bureau for Economic Policy Analysis
Abstract
We use
very detailed microdata on fiscal contributions and benefits of the entire
population to calculate the discounted lifetime net contribution of the
immigrant population present in The Netherlands in 2016. We differentiate by
immigration motive and up to 87 source regions. Labour migrants' net
contribution is positive, study, family and asylum immigrants' contributions
are negative. Second generation scholastic performance scores at age 12 by
social background are similar to scores for native Dutch children, highest
education attained for given test scores is also similar, but incomes for given
education levels are lower, and so are net contributions. The gap between net
contributions of individuals with immigrant background and without immigrant
background does not root in attained levels of schooling but in the benefits
from schooling. Regional cultural distance to Protestant Europe is associated
with large fiscal net contributions.
Keywords:
fiscal incidence, immigrants, cultural distance
License
Information
The
copyright holder has granted SSRN a license.
All rights reserved. No reuse allowed without permission.
JEL
Classification: H5, J6, J15
Suggested
Citation:
van de
Beek, Jan and Hartog, Joop and Kreffer, Gerrit and Roodenburg, Hans, The
Long-Term Fiscal Impact of Immigrants in the Netherlands, Differentiated by
Motive, Source Region and Generation. IZA Discussion Paper No. 17569, Available
at SSRN: https://ssrn.com/abstract=5077481
Why
Europe Is Burning
Young
Europeans are taking to the streets in Paris, Madrid, and Brussels. They say
they want more investment in schools and housing. They should be protesting a
system rigged for their grandparents.
Oct 19, 2026
https://niallferguson.substack.com/p/why-europe-is-burning
“The most French
thing I’ve ever seen” was a couple sipping wine in a sidewalk café,
probably discussing Jean-Paul Sartre, while a fire started by protesters raged
on the other side of the boulevard. Disappointingly, the video posted on X was
from three years ago, but it suited the moment last week.
As their
national anthem contains the phrase, “Aux armes, citoyens!,” don’t be
surprised if, quite regularly, young French people decide to reenact
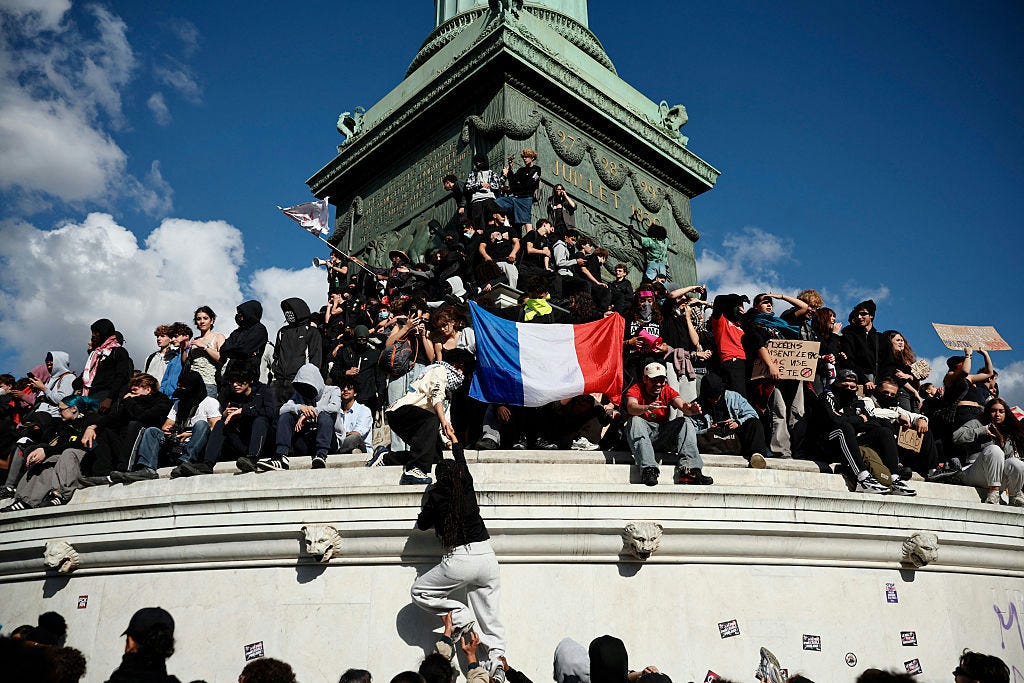
revolutionary scenes. As I write, French schools
are burning—set ablaze by high schoolers who say they want more
investment in education but for some reason think they can achieve this by
filling the streets with garbage, setting it on fire, waving Palestinian flags,
and clashing with the police. The latest reincarnations of the sans-culottes
are out in force—though, as in 1968, their attire is quite chic. As a cynical
friend observed, what the first Communion is for a young Roman Catholic, so the
first manifestation is for a young Parisian: a rite of passage.
And yet it’s
not just France. The kids are out in the streets
of Madrid, too, incensed (they claim) about a growing housing crisis. In
Brussels the burning issue is government budget cuts.
So what’s
going on in Europe?
No, I don’t
think it’s the beginning of Eurozone Crisis 2.0. Those with good memories will
recall that the first Eurozone crisis began in 2009 with a Greek debt crisis
that spread to other countries. As we shall see, the recent wave of protests
has indeed coincided with a French debt crisis that also threatens to spread to
other members of the Eurozone. However, if the European Central Bank (ECB)
learned anything from the events of 2011–2012 it was that it must stand ready
“to do whatever it takes to preserve the euro”—the
immortal words of ECB president Mario Draghi in July 2012. If French
bond yields go up much higher—say by another 100 basis points (1 percent)—then
the ECB has the tools to intervene and stabilize the market.
No, rather
than a financial crisis, what we see today is more like synchronized political
crises in multiple European countries. France will elect a new president on
April 18, and it looks as if the far-right Marine Le Pen could finally win at
the fourth attempt. In Spain, the leftist prime minister Pedro Sánchez has just
called snap elections for November 29; I expect him to lose. In Germany,
Chancellor Friedrich Merz lurches from crisis to crisis as the far-right
Alternative für Deutschland keeps
winning regional elections. In Italy, Giorgia Meloni needs an election
soon, before any more of her coalition’s supporters defect to Roberto
Vannacci’s authentically fascist Futuro Nazionale.
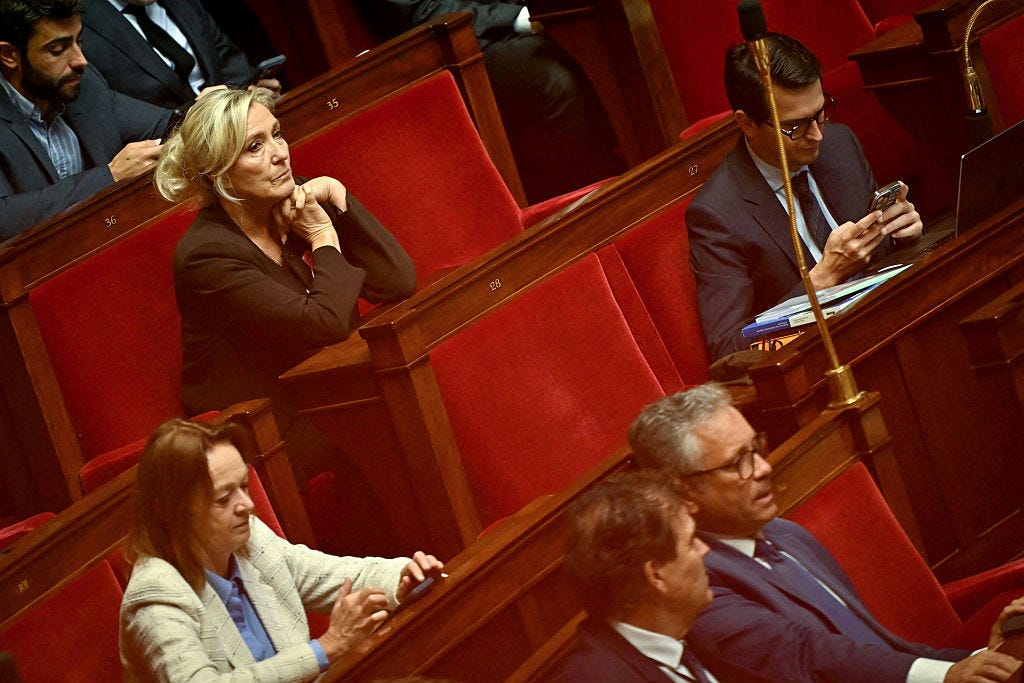
Rassemblement
National president Marine Le Pen (third from left) attends a session during
RN’s parliamentary window in Paris on October 8, 2026. (Lou Benoist/AFP via
Getty Images)
The fact
that young people are setting wheelie bins on fire is in some ways a
distraction from the root causes of all this political instability. For,
despite the echoes of 1789, 1830, 1848, 1871, and 1968, when youthful
revolutionaries challenged Europe’s established order, the generational
politics of 2026 is very different. Today, by historical standards, the young
are an endangered species. They are dimly aware that they are being screwed,
but they don’t appear to understand who’s doing the screwing.
A clue for
the European young: It’s not Donald Trump or Benjamin Netanyahu or whoever else
you want to burn in effigy. Mais, non: It’s your grandparents.

Let’s begin
with the proximate cause of this crisis, which is, admittedly, the war that
Trump and Netanyahu launched against Iran at the end of February, and the
resulting economic strife. After more than seven months, that war is still not
over. Indeed, in some ways it has escalated, in that the Houthi rebels have
joined in the fun by attacking the Saudi pipeline to the Red Sea and now
launching missile strikes on Riyadh’s airport. Meanwhile, despite a sustained
effort by the United States to collapse the Iranian economy, the Islamic
Revolutionary Guard Corps still has enough firepower to disrupt shipping
through the strait, reversing the recovery we have seen in recent weeks.
This oil
shock has not been as economically disruptive as the comparable supply
disruptions of 1973–1974 and 1979. Prices of natural gas in Asia and Europe are
more than double their prewar level, but oil has been less impacted. Diesel
prices are up more than gasoline. The most significant economic impact of the
war is that bond yields are back to where they were before the 2008–2009 global
financial crisis.
Economists
like to argue about why long-term interest rates have risen. Is it because
people expect higher inflation? Is it because governments are competing with
artificial intelligence investors for a finite amount of capital? For our
purposes, all that matters is that the rate at which the French government
borrows money for 10 years has risen from 3.22 percent on the eve of the Iran
war to 4.87 percent at the Friday close. An increase of more than 1.5
percentage points may not sound like much, but that’s a 50 percent jump in
borrowing costs—and it’s a serious problem when the gross public debt has
reached 119 percent of GDP. If France’s more or less paralyzed National
Assembly cannot pass a budget in the coming weeks, the deficit in 2027 will be
around 6.5 percent of GDP.
Yes, I know:
Everyone’s bond yields have gone up, including Uncle Sam’s. Indeed, the U.S.
10-year Treasury yield was yielding 5.22 percent on Friday, higher than the
French. And the U.S. deficit for 2027 will be about the same as the French. The
difference is that the U.S. economy is growing at 6.3 percent nominal
(including inflation). The equivalent number for France? It’s 1.9 percent. When
growth is above the interest rate, you’re okay. When it’s the other way round,
you’re heading for a crisis.
France is
not alone. In both Italy and the United Kingdom, the cost of government
borrowing is higher than the nominal growth rate. What has gone wrong? Here’s
where grandma and grandad come in. The French (and British and Italian) fiscal
crisis is at root due to generational imbalances in welfare and tax systems,
exacerbated by reflexive Keynesian spending every time anything nasty happens
(a financial crisis, a pandemic, a war, an energy shock).
These are no
countries for young men. (The same, by the way, is true of most of East Asia.)
Since 1960, across the 38 advanced economies that belong to the Organization of
Economic Cooperation and Development (OECD), the old-age dependency ratio
(people age 65 and over per 100 people ages 15 to 64) has doubled from around
15 to around 30, while fertility has plunged from 3.3 to 1.5.
Youth just
matters less than it used to. The age group that historically is most inclined
to riot is 15 to 24. Back in 1968, that was a significant proportion of the
French (and South Korean) population: 16 percent and 18 percent respectively.
Today, the youth share is much lower—12 percent and below 10 percent—whereas in
India it has grown from 16.6 percent to 17.5 percent. That helps explain why
India’s “cockroach” movement, a student protest
movement, has been so much more politically effective than today’s
French school protests.
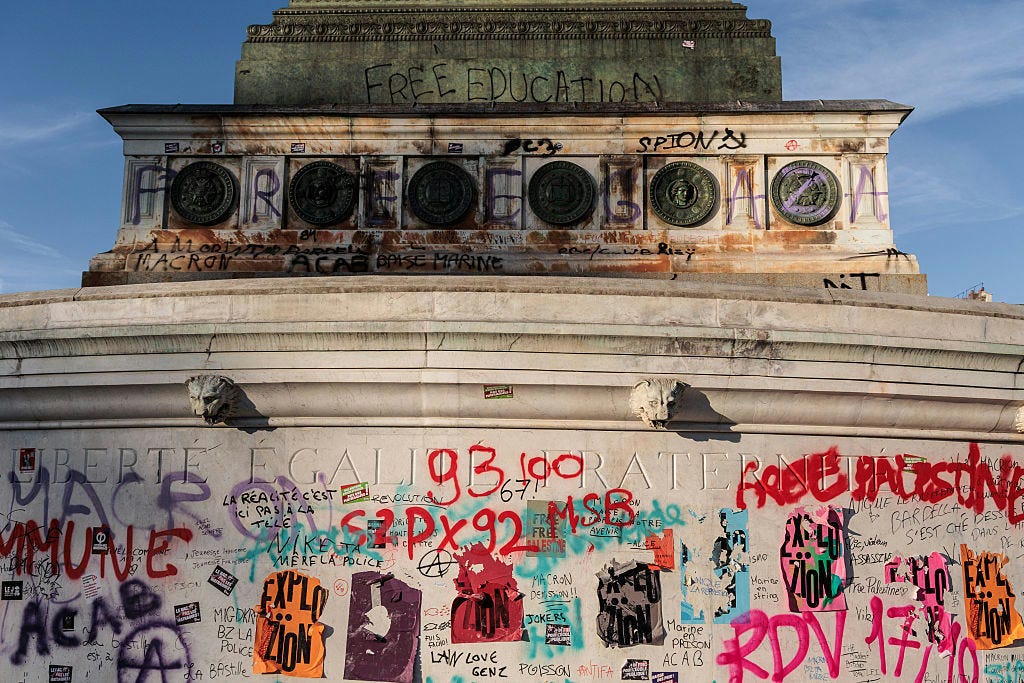
The July
Column, in the center of the Place de la Bastille, stands vandalized and
covered in graffiti in Paris, France, on October 8, 2026. (Gauthier
Bedrignans/Hans Lucas/AFP via Getty Images)
As is well
known, Europe has relatively generous welfare systems, which do more taxing and
redistributing than their U.S. equivalents. It’s just that these systems were
designed for 2.5 children per family and an average life expectancy of 62, not
1.25 and 79. With a few exceptions, the various European models are in the
early phase of a nosedive into insolvency.
To be sure,
aging isn’t the sole driver of rising public debt. It explains about two-fifths
of the increase since 2000. The rest is due to debt-financed spending in
response to the financial crisis, Covid-19, and other crises; tax cuts and
discretionary spending; and the rising cost of paying interest on the debt. And
the aging problem varies from country to country. No European country is aging
as fast, nor reducing fertility as much, as Japan and South Korea.
This aging
trend is not about to stop. Across the OECD, the dependency ratio is forecast
to rise from 32.6 seniors per 100 people of working age in 2024 to 55.2 in
2054—a 69 percent increase. The working-age population will decline by 13
percent over the next four decades across the OECD. (In Italy, Latvia,
Lithuania, and Poland the decline will exceed 35 percent.)
This is not
primarily a problem of public pensions—the original government welfare program,
introduced by the German chancellor Otto von Bismarck in 1889. The OECD’s
latest projections have average public pension spending rising from 8.8 percent
of GDP in 2023–2024 to 10 percent in 2050—not a crippling increase. This is
because most countries (not all) have acted in various ways to cap the costs of
public pensions, either by reducing benefits, restricting coverage, or raising
retirement ages.
The real
problem is the cost of elderly healthcare. The European Commission’s 2024 Ageing
Report estimated that total age-related expenditure—pensions,
healthcare, long-term care, and some other age-related items—would rise by
about 1.2 percentage points of GDP between 2022 and 2070 in its baseline
scenario, reaching 25.6 percent of GDP by 2070. However, under less rosy
assumptions about healthcare and long-term care, the increase could be three
times higher (roughly 3.9 percentage points).
In essence,
politicians on both sides of the English Channel have gotten into the very bad
habit of bribing seniors based on the observation that they are increasingly
numerous and have relatively high turnout rates in elections. Spending on the
over-65s has risen in Britain by 2.5 percentage points of GDP since 2000; the
French figure is close to 3 percent. In both France and Britain, median
incomes, adjusted for inflation, have risen almost half as much again for
over-64s as for 18 to 64s. In other words, it has paid better in both countries
to be retired than to be employed.
Young
people will set more things on fire; if not their own schools, then
asylum-seekers’ hotels and synagogues as a rising share of young men swing to
the far right.
Since 2000,
the public cost of healthcare and other care for Britain’s over-65s has
doubled. A disastrous Liberal Democrat policy, adopted by the
Conservative-Liberal coalition in April 2011, committed the government to
increase the state pension by whichever was the highest of inflation, wage
growth, or 2.5 percent (the so-called “triple lock”). Sir Keir Starmer’s
government suffered its first serious reverse when his chancellor of the
Exchequer, Rachel Reeves, was forced to reverse plans to means-test pensioners’
winter heating subsidies. Starmer’s successor, Andy Burnham, has said he will
modify the “triple lock”—but not until after the next election, and even then
only in a limited way. (The rate of wage growth will still be considered, but
not on an annual basis.) Exemplifying the problem, Burnham has already
committed to blowing the savings on a new National Care Service. Because why
not add another entitlement before the ship of state goes under?
And yet
you’d rather be Britain than France, and not just because there are a lot more
French oldies than British oldies, and a lot more young Brits than young Frogs.
(The unique
British pathology is the ludicrously high proportion of young people
living on benefits such as “personal independence payments,” dished out to
anyone feeling a bit depressed.) The French rioters say their principal
grievance is under-investment in schools. But it should really be
over-investment in French retirees. For a time, until very recently, according
to the Financial
Times, “over-65s [had] higher average incomes than the working age
population—unique both internationally and in France’s own history.” When
President Emmanuel Macron proposed to raise the French retirement age, it was “aux
armes, citoyens” yet again. Two successive governments fell over the issue.
The United
States has its own version of these problems. Roughly a third of the
deterioration of the U.S. federal deficit since 2007 can be attributed to the
aging of the population. And yet, as The Wall
Street Journal reported last week, “Wealth increased 37 percent for
Americans 75 and older, while it declined 23 percent for people under 35.
During this period, people 75 and older became the richest age group, with a
median net worth of $505,000.” It’s the boomers’ world, and young people just
get to rent in it. In a separate piece (as if to rub it in), the Journal
enthused: “ ‘Superagers’
Are Living—and Thriving—Long Past 80.” One of them is in the White
House.
One fine
day, it will be the painful task of some heroic, one-term president to grasp
the third rail of Social Security and Medicare reform. But that day is not
tomorrow. In France, the day of reckoning is here and now.

Unfortunately,
the French Fifth Republic is ill-equipped to meet the challenge. The vocabulary
of European politics rules out the sentence: “We need to reform seniors’
entitlements so that we don’t go bankrupt.” Instead, the left offers socialism
and the right serves up national socialism. The left lays the blame on
billionaires, whom they will tax to pay for yet more benefits. The right lays
the blame on immigrants, whom they will deport as if that will help matters.
Apart from that difference, there is a horseshoe forming in Western politics:
At the extremes, socialism and national socialism are converging on economic
issues (industrial policy, public ownership, rent controls), not to mention
foreign policy (blame Israel for everything). Of course, these tired old ideas
bear almost no relation to economic reality.
So what
happens? I think young Europeans have been so successfully indoctrinated in
school and college that they’ll blame almost anyone for their dissatisfaction,
except the people who are actually responsible: namely seniors and the
politicians who rely on their votes. So instead of voting for (if such a thing
existed) a European version of Argentina’s Javier Milei—who campaigned for
radical fiscal reform precisely to create better opportunities for the
young—they’ll try the old, been-there-done-that solutions, and the results will
be a weaker euro, more inflation, downgrades by the rating agencies, and even
higher interest rates.
As a result,
despite their fine pledges to spend more on national security, few European
governments will modernize their air defenses in the way they clearly need to
as the Russian drone menace extends beyond Ukraine. A shocking amount of
European defense spending goes to—you guessed it—the pensions of retired
military personnel.
Young people
will set more things on fire; if not their own schools, then asylum-seekers’
hotels and synagogues as a rising share of young men swing to the far right.
That will achieve precisely nothing, except to expedite the capital flight.
Every government will have a half-life of 12 months.
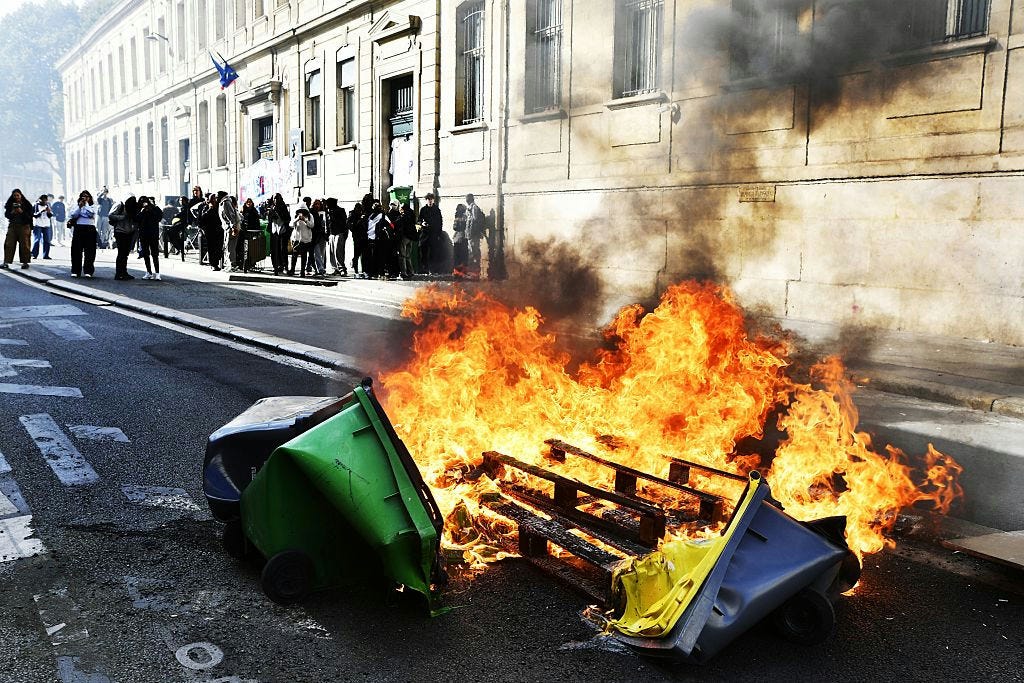
Trash
cans burn during a blockade of Colbert high school in the 10th arrondissement
of Paris, France, on October 8, 2026. (Frederic Vielcanet/Gamma-Rapho via Getty
Images)
Fiscal
reforms are doubly hard if you also have a multiethnic population and a
multiparty political system. It is a well-known fact that Americans have
retained the two-party system for all intents and purposes (I leave for another
day the mystery of the registered “Independents”). That is not true in Europe.
The Croats have 21 parties in their national legislatures. The Dutch have
around 17. The Spaniards have about 13, the Italians nine, the Greeks seven. I
could go on.
Less
well-known is that, in marked contrast to the last 200 years, the major
European states are now as multiethnic as the United States. The foreign-born
share of the American population is 16 percent, an all-time high. However, the
figures for the UK, Spain, and Germany are even higher. The great migration to
Europe that culminated in the decade 2015–2024 was motivated partly by an
economic theory: that aging societies needed young blood. Future historians
will marvel at the scale of this miscalculation.
In The Constitution of Liberty
(1960), the great classical liberal economist Friedrich A. von Hayek predicted
that “concentration camps for the aged unable to maintain themselves are likely
to be the fate of an old generation whose income is entirely dependent on
coercing the young.” He could not have been more wrong. The aged have
conclusively won the war of the generations in Europe. What we are witnessing
is merely the death throes of a dream.
“Bliss was
it in that dawn to be alive,” wrote
William Wordsworth, recalling his youthful enthusiasm for the French
Revolution, “But to be young was very heaven!” He was just 21 when he visited
revolutionary France in 1791. What would he write if he could see Paris today?
“Bliss was
it that eve to be alive, But to be old was very heaven!”
This
essay first appeared in The Free Press on October 12, 2026

Niall
Ferguson: Why Europe Is Burning
In his
October 2026 article "Why Europe Is Burning," published in The
Free Press, prominent historian and geopolitical commentator Niall
Ferguson argues that the violent student protests and growing civil
unrest sweeping through cities like Paris, Madrid, and Brussels are the
symptoms of a deep-rooted
generational war that
younger Europeans have already lost.
Rather than
a simple outcry for better education or housing, Ferguson diagnoses the
instability as the fallout of an unsustainable political and economic framework
rigged entirely against the youth. His core arguments center on three major
structural failures:
1. The
Generational War and a "Rigged" System
Ferguson
asserts that European public finances and political systems are fundamentally
engineered to benefit seniors and retirees at the expense of the young.
2. The
Great Migration Miscalculation
Ferguson
strongly critiques the economic theory driving Europe's immigration policies
from 2015 to 2024.
3.
Economic Decline and Capital Flight
The
trajectory of these protests, according to Ferguson, guarantees a grim economic
future for the Eurozone.
Ultimately,
Ferguson views the current unrest not as the dawn of a new revolution, but as
the chaotic "death throes" of the European dream—shattered by
demographic collapse, fiscal insolvency, and broken integration